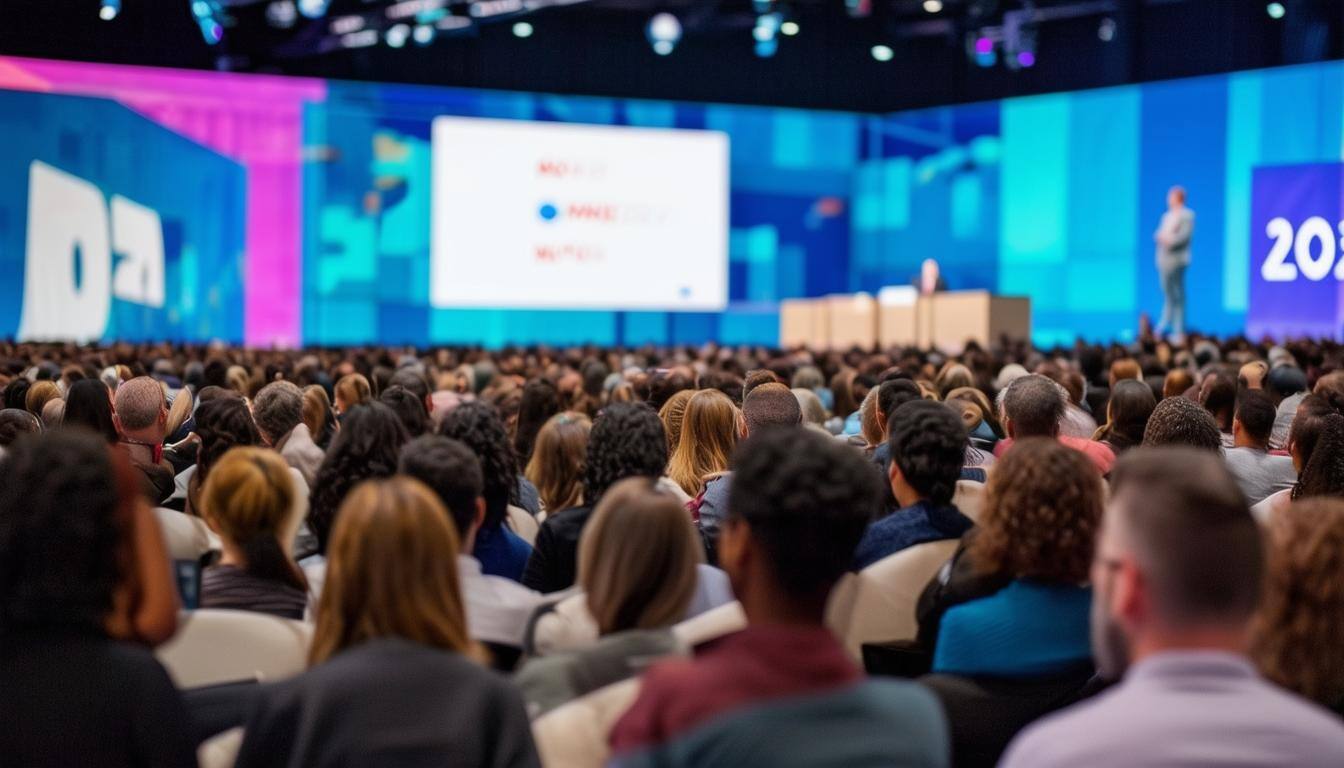
Money20/20 USA returns for the last time to The Venetian in Las Vegas October 18-21, 2026. This year the organizers built the agenda around four content pillars:
- Borderless Financial Architecture: cross-border modernization, tokenization, and stablecoins
- Technology as the Great Equalizer: agentic AI, AI-predicted fraud, hyper-personalization, and digital identity
- Partnerships as the Engine to Scale: the bank-fintech relationships that decide which products actually reach market
- Brave New World: Setting Guardrails: trust, transparency, and regulatory clarity across digital assets, AI, and data
Just two years ago, the agenda was about fintech growing up: rebundling, reaching profitability, and AI moving from hype toward utility. This year, the pillars point somewhere more concrete. Money is getting programmable, software is starting to act on customers' behalf (agents!), and generally, the rules are being written in real time.
These are the three shifts we think matter most for banks and fintechs, and what they mean for the year ahead.
1. Money Is Becoming Programmable
For years, stablecoins and tokenized assets lived on the “crypto side” of the Money20/20 show floor. In 2026 they sit in a dedicated content pillar about global commerce. The show frames real-time cross-border payments as a top priority, with tokenization and stablecoins being actively explored to make transactions faster and cheaper.
What it means for the industry: The bigger change is what programmable money makes possible on top of the payment itself. Banks that treat tokenization purely as back-office plumbing risk handing the customer-facing upside to someone else. Banks should start asking now which customer experiences can get better when settlement is instant and money can follow rules.
Recommended sessions:
- Programmable Dollars Move in Real Time
- The Realtime Rails the Banks Still Own (and How They're Adopting Rails They Don't)
2. The Next Customer Might Be an Agent
The "Technology as the Great Equalizer" pillar puts agentic AI front and center, along with AI-predicted fraud, hyper-personalization, and digital identity. Since last year, the conversation has moved from whether autonomous agents can work, to who is accountable when they act.
That question gets real quickly when we talk about commerce. AI is already researching products, comparing prices, and in some cases completing checkout. Every one of those purchases still runs on a card or account a bank issued. Meanwhile, fraud is scaling with the same tools: consumers across 42 markets lost roughly $442 billion to scams in a year, according to the Global Anti-Scam Alliance's Global State of Scams 2025.
What it means for the industry: Banks and fintechs need to plan for two audiences at once: the human cardholder and the software acting for them. That means making credentials, identity checks, and benefits legible to agents, so a customer's card perks and rewards still show up when an assistant does the shopping. If a bank's value proposition only appears when human eyeballs are looking at the screen, it rapidly becomes invisible in an agent-led purchase.
Recommended sessions:
- Is Acting a Responsibility Too Far for Agents?
- Agentic Commerce: A Payments & Infrastructure Reality Check
3. Bank Growth Runs Through Partners, So Trust Has to Be Built In
Two of this year's pillars come back to the same basic point. "Partnerships as the Engine to Scale" reflects that most banks no longer build every product in-house. Fintech partners now power everything from payments to rewards to lending, and those relationships increasingly decide what reaches customers. The pillar "Brave New World: Setting Guardrails" reflects that the rules for those products, especially around AI, data, and digital assets, are still being written.
Fast-moving fintechs working with regulated banks creates real tension. While banks need partners to move fast, every partner they add becomes part of their regulatory and reputational footprint. So if a partner mishandles data or runs afoul of a new rule, the customer blames the bank.
What it means for the industry: Choosing a partner is becoming as much a risk decision as a product decision. To protect themselves, banks will continue to favor partners with clear disclosures, auditable data practices, and a track record of compliance, even if that means slower time-to-market. Fintechs that make diligence easy, with documentation and compliance built into the product, will move through bank procurement faster. And banks will get better results by bringing compliance into early partner conversations instead of after the deal is signed.
Recommended sessions:
- Build vs Buy? The gameplan for regional expansion
- Inside the Vault: Life and Death of Partner Banking
While You're There... Come Visit Wildfire
We hope your week at Money20/20 USA is productive and full of good conversations. We'd love to have one with you. Join us in our trademark Venetian Pool Cabana and help us offer a proper send-off in our last year there!